HMRC SA302 & Tax Return Certified Translation UK: Home Office Visa Guide 2026
Navigating the financial evidence requirements for United Kingdom immigration applications requires meticulous attention to fiscal documentation, statutory compliance, and linguistic precision. When an applicant or their sponsor relies on foreign self-employment income, overseas corporate earnings, freelance dividends, or international fiscal records to fulfill the stringent financial criteria stipulated under the UK Immigration Rules, submitting foreign-language tax assessments without an accredited, compliant certified translation is one of the most frequent causes of catastrophic visa refusals. The United Kingdom Visas and Immigration (UKVI) department and the Home Office impose uncompromising legal standards on all fiscal evidence. Whether you are submitting tax calculations to satisfy Appendix FM for a Spouse Visa, verifying supplementary income under Appendix Skilled Worker, or proving substantial historic business earnings for an Innovator Founder or Global Talent endorsement, obtaining an official HMRC SA302 and tax return certified translation in the UK is an indispensable requirement for legal compliance and evidentiary validity.
Understanding the HMRC SA302 Tax Calculation and Its Foreign Equivalents
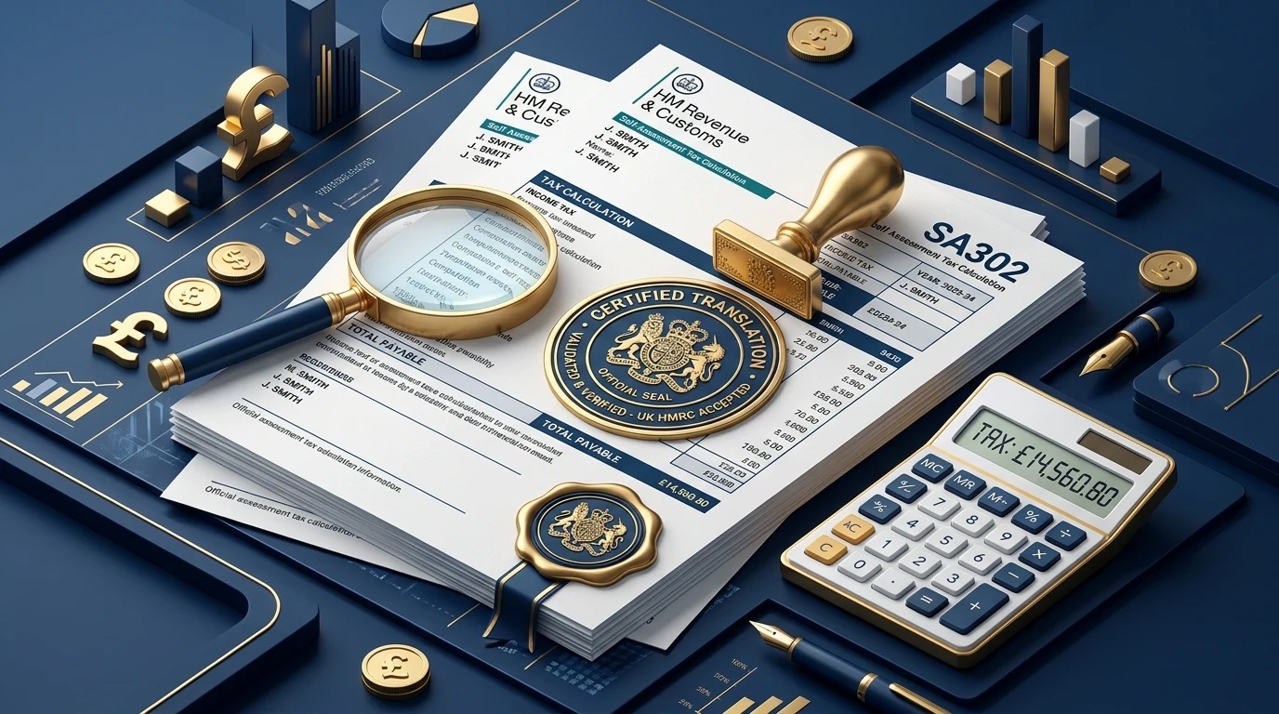
Within the United Kingdom's tax infrastructure administered by His Majesty's Revenue and Customs (HMRC), an SA302 is an official summary calculation that details an individual's total taxable income, deductions, allowances, and the final tax liability calculated from their annual Self-Assessment tax return. For domestic applicants living and working in the UK, the SA302—when paired with the corresponding Tax Year Overview—serves as the definitive gold standard of verified earnings. Caseworkers at the Home Office rely upon this computation because it reflects calculations processed and validated directly by HMRC rather than unverified self-reported figures.
However, tens of thousands of UK visa applications each year rely upon financial earnings generated outside the United Kingdom. In these cross-border scenarios, the Home Office requires the overseas applicant, their foreign spouse, or their commercial enterprise to produce the official statutory equivalent of the HMRC SA302 issued by their domestic national revenue authority. These official fiscal instruments vary widely across global tax jurisdictions:
- United States: Official IRS Tax Return Transcripts, Form 1040 computations, and Schedule C/SE filings validated by the Internal Revenue Service.
- Canada: Notice of Assessment (NOA), Notice of Reassessment, and T1 General Income Tax and Benefit Return issued by the Canada Revenue Agency (CRA).
- Australia: Notice of Assessment and Individual Tax Return records verified by the Australian Taxation Office (ATO).
- European Union: Annual income tax assessments (such as the Avis d'imposition sur les revenus in France, the Einkommensteuerbescheid in Germany, or the Certificazione Unica / Modello Redditi in Italy).
- South Asia & Middle East: Formal income tax assessment orders, National Tax Number (NTN) annual computation returns, and corporate audited tax disclosures.
Because these foreign statutory tax documents are frequently composed in languages other than English or Welsh, they cannot be evaluated by UKVI caseworkers without a fully compliant, certified English translation that adheres strictly to the statutory evidentiary criteria laid down in the UK Immigration Rules.
Statutory Criteria for Certified Translations Under UKVI and Home Office Rules
The Home Office maintains explicit, non-negotiable guidelines regarding the translation of all official evidentiary documents submitted in support of visa, settlement, and nationality applications. In accordance with the official UKVI evidentiary guidance, every non-English tax computation, SA302 equivalent, and self-assessment filing must be accompanied by an official certified translation that fulfills each of the following statutory requirements:
Official UKVI Certified Translation Criteria Checklist (2026)
- Formal Statement of Truth: The translation must include an explicit written declaration by the translator or authorized translation agency confirming that it is a "true and accurate translation of the original document".
- Professional Credentials and Accreditation: The certified translation must explicitly record the full name, professional qualifications, and institutional affiliations of the translator or translation management organization (e.g., membership in the Institute of Translation and Interpreting - ITI, the Chartered Institute of Linguists - CIOL, or the Association of Translation Companies - ATC).
- Contact Information: The official physical business address, email, and telephone contact information of the translator or agency must be visibly printed on the formal statement.
- Execution Date and Signature: The document must feature an original or secure cryptographic digital signature alongside the exact date of execution.
- Complete and Unabridged Reproduction: Every section, footnote, tax code table, fiscal stamp, watermarked serial number, and official calculation note in the original tax filing must be fully translated without omissions, editorial summaries, or alterations.
Submitting an informal, machine-translated, or self-translated fiscal document—even if the applicant is completely fluent in both languages—results in instantaneous rejection under the validity provisions of paragraph 34BB and general grounds for refusal under Part 9 of the UK Immigration Rules.
UK Visa Categories Demanding Certified SA302 and Tax Return Translations
Certified tax documents represent the backbone of financial scrutiny across numerous UK visa pathways. Caseworkers evaluate certified fiscal filings to confirm whether the applicant or sponsor meets mandatory financial thresholds, complies with statutory business activities, or demonstrates persistent economic self-sufficiency.
1. Appendix FM: Spouse, Civil Partner, and Family Visas
Under Appendix FM of the UK Immigration Rules, applicants sponsoring a spouse or partner must satisfy the Minimum Income Requirement (MIR), which currently stands at £29,000 gross per annum. When the sponsor or applicant relies on self-employment income (Category F or Category G) or director earnings from a specified limited company, the evidentiary requirements set forth in Appendix FM-SE are extraordinarily demanding.
Under Category F (income from the last full financial year) and Category G (an average of the last two full financial years), the applicant must furnish:
- The full annual Self-Assessment tax return.
- The formal HMRC SA302 computation or verified foreign tax equivalent.
- The official Tax Year Overview confirming that all assessed taxes have been settled or are on an approved payment plan.
- Audited annual accounts and comprehensive company tax computations where director dividends are claimed.
If any portion of these self-employment earnings was generated through overseas commercial operations, foreign freelancing contracts, or offshore consultancies, every single line item of the foreign tax assessment must be translated into English by an accredited certified translator.
2. Appendix Skilled Worker & Health and Care Visas
While the primary evidentiary basis for a Skilled Worker visa is a valid Certificate of Sponsorship (CoS) issued by an approved licensed sponsor, certified tax computations become paramount in several nuanced circumstances. When applicants transition between employers, claim supplementary allowable earnings, or demonstrate continuity of income during disputed sponsorship periods, certified historic tax returns provide definitive proof of past earnings and legal compliance.
3. Global Talent and Innovator Founder Visas
Applicants pursuing endorsement under the Global Talent route (across digital technology, science, arts, or research) or the Innovator Founder route must demonstrate exceptional promise or exceptional talent. In many endorsement applications submitted to bodies such as Tech Nation / Founders Forum, the British Academy, or Innovator Founder endorsement bodies, proving substantial market traction requires submitting certified tax computations that verify multi-million pound enterprise revenues, commercial licensing royalties, or high-level executive remuneration earned overseas.
4. Indefinite Leave to Remain (ILR) and British Nationality
When applying for permanent settlement (ILR) or naturalisation as a British Citizen, applicants must satisfy the Good Character requirement and prove continuous lawful residence without fiscal irregularities. The Home Office frequently conducts automated tax checks with HMRC. If historic income declarations on past visa applications diverge from recorded tax returns, applicants are required to submit certified, comprehensive tax reconciliation returns to resolve discrepancies and avoid refusal under paragraph 9.7.1 (deception or false representations).
Legal Deep-Dive: Appendix FM-SE Paragraph 7, Paragraph 13, and Paragraph 19
Immigration law practitioners and applicants must pay strict heed to the statutory mechanics embedded in Appendix FM-SE of the UK Immigration Rules. Caseworkers do not exercise general discretion when assessing financial records; they apply a binary compliance test against the explicit paragraphs of the immigration rules:
Paragraph 7: Self-Employment as a Sole Trader, Partner, or Franchisee
Paragraph 7 governs all individuals relying on non-corporate self-employment income. The rule dictates that the gross taxable income claimed must be corroborated by the relevant tax return and official tax assessment computation covering the entire financial year. If an applicant conducted trade outside the UK, the caseworker must be provided with the exact foreign statutory instrument demonstrating that the revenue was declared to the competent fiscal jurisdiction. The certified translation must translate every fiscal schedule, including cost of goods sold, motor expenses, allowable travel expenses, capital allowances, and net trading profits.
Paragraph 13: Specified Limited Companies in the UK and Abroad
Paragraph 13 applies whenever an applicant or their sponsor acts as a director or employee of a specified limited company (a company in which shares are held directly or indirectly by the applicant, their partner, or their immediate family). In such cases, personal bank statements alone are completely invalid. The applicant must submit:
- The company tax return (CT600 in the UK or foreign equivalent) covering the same financial period.
- The certified annual audited accounts showing full balance sheets, profit and loss statements, and director notes.
- Official corporate registration certificates showing share ownership percentages.
- Personal SA302 calculations proving that dividend distributions and PAYE director salaries were declared personally.
When corporate accounts are drafted in languages such as French, Arabic, Mandarin, or Spanish, translating the entire 30-to-50-page financial packet with exact balance sheet alignment is essential to satisfy Paragraph 13 mandates.
Paragraph 19: Evidentiary Flexibility and Rejection Triggers
Under Paragraph 19 of Appendix FM-SE, caseworkers are granted limited discretion to request missing documents only if a document in a sequence is missing or if a document submitted contains a minor administrative defect. However, the Home Office guidance explicitly clarifies that failure to provide an English translation of a foreign document is NOT considered a minor defect. If a foreign tax document is uploaded without an accompanying accredited certified translation, caseworkers are legally instructed to disregard the document entirely, leading to immediate refusal without prior clarification letters.
Comparative Analysis: SA302 vs Tax Year Overview vs Self-Assessment Return
Applicants frequently confuse the distinct tax documents issued by revenue authorities. To guarantee that your immigration filing satisfies UKVI evidentiary standards without ambiguity, the table below provides a comprehensive structural comparison of these three essential tax instruments:
| Tax Instrument | Issuing Authority | Core Content & Purpose | Evidentiary Weight for UKVI | Translation Imperatives |
|---|---|---|---|---|
| SA302 Calculation | HMRC / Foreign National Tax Agency | Comprehensive breakdown of taxable income across all schedules (employment, dividends, property, capital gains) and final tax liabilities. | Mandatory Gold Standard: Directly proves official state validation of claimed earnings. | Full unabridged translation of all tax computation brackets, relief allowances, and statutory authority references. |
| Tax Year Overview | HMRC / National Tax Treasury | Ledger summary proving whether the assessed tax liability was paid, outstanding, or subject to formal surcharge. | Crucial Corroboration: Confirms that earnings were lawful and taxes were fully settled. | Translation of payment reconciliation status, receipt dates, reference numbers, and nil-balance clearances. |
| Self-Assessment Return (SA100 / Form 1040) | Submitted by Taxpayer / Accountant | The detailed annual return form declaring gross revenues, allowable business deductions, and personal expenses. | Supporting Context: Explains the itemized operational data underlying the final SA302 calculation. | Translation of business schedules, profit and loss attachments, accounting declarations, and submission timestamps. |
Translating Complex Fiscal Schedules: Capital Gains, Foreign Property, and Dividends
Standard translators who lack specialized financial accounting qualifications often make grave errors when handling complex fiscal documents. Tax computations are not merely narrative texts; they contain dense mathematical tables, statutory statutory code references, and nuanced legal distinctions. Below are three specialized tax schedules that demand extreme linguistic and fiscal precision:
1. Capital Gains Tax (CGT) Computations
When an applicant relies on cash savings derived from the sale of overseas real estate or equities under Appendix FM (Category D - Cash Savings), they must prove that the funds have been held under their personal control for at least six months and were acquired legally. Official tax assessments proving payment of foreign capital gains tax provide decisive proof of lawful acquisition. Certified translations must clearly delineate between gross sale proceeds, allowable acquisition costs, indexation allowances, taper relief, and net chargeable gains.
2. Overseas Property Rental Schedules
Income generated from overseas rental portfolios can be counted toward the financial requirement under Category C (Non-Employment Income). The applicant must present the foreign tax schedule showing gross rental income, mortgage interest deductions, property management maintenance fees, and net taxable property income. Translators must avoid confusing gross rental yield with net taxable profit, as UKVI caseworkers assess only the net profit figure reflected on official tax documents.
3. Foreign Dividend Vouchers and Corporate Profit Allocations
For corporate directors receiving distributions from foreign operating entities, the certified translation must clearly cross-reference the company's fiscal year-end date with the personal dividend tax assessment date. Misaligned tax accounting periods between the corporate entity and the personal shareholder can trigger suspicions of artificial earnings inflation. The certified translation must accurately replicate dividend tax credits, withholding tax deductions, and net distributed dividends.
Comprehensive Real-World Case Studies
To illustrate how certified tax computations and SA302 translations operate in practice, review these three detailed immigration case scenarios managed under current UKVI evidentiary rules:
Case Study 1: Dual US-UK National Sponsoring a Foreign Spouse (Appendix FM)
The Scenario: A British-American dual citizen living in New York relocated back to London to sponsor their non-EEA spouse. The sponsor had worked as an independent software consultant in New York for the previous two years, earning over $120,000 annually. To satisfy Category F, the sponsor submitted their US Federal Tax Return (Form 1040), Schedule C (Profit or Loss from Business), Schedule SE (Self-Employment Tax), and their official IRS Tax Return Transcript.
The Evidentiary Challenge: While the US documents were in English, the sponsor also had consulting revenues earned through an entity in Bogotá, Colombia, documented via Colombian DIAN tax certificates drafted entirely in Spanish. Furthermore, the UK caseworker needed to verify how the Colombian taxable income correlated with the IRS Form 1040 foreign earned income exclusion (Form 2555).
The Solution: Lang247 performed a full certified translation of the Colombian DIAN tax assessments, including all statutory tax brackets, municipal withholding tax slips, and corporate banking reconciliations. The translation package featured an official Statement of Truth, CIOL registration credentials, and an itemized currency conversion table applying official HMRC average exchange rates. The Spouse Visa was granted without a single Request for Evidence (RFE).
Case Study 2: European Medical Specialist Registering with the GMC and Applying for Health and Care Worker Visa
The Scenario: A specialist surgeon from Lyon, France, received an offer of employment from an NHS Foundation Trust in Manchester. Prior to issuance of the Certificate of Sponsorship (CoS), the General Medical Council (GMC) and NHS vetting board required five years of verified medical earnings, hospital consultancy invoices, and French national tax assessments (Avis d'impôt sur les revenus) to corroborate clinical experience and financial probity.
The Evidentiary Challenge: French tax returns contain intricate terminology regarding liberal profession regimes (BNC - Bénéfices Non Commerciaux) and mandatory social security contributions (URSSAF). An inexperienced translator translating BNC as "non-commercial benefits" would create profound confusion regarding the doctor's legitimate commercial earnings.
The Solution: Lang247 deployed a specialized legal-financial translator who accurately rendered BNC as "Net Professional Self-Employed Earnings (Liberal Profession Regime)", providing clear explanatory footnotes for NHS compliance officers. The GMC completed registration, and the Health and Care Worker visa was approved in five working days.
Case Study 3: Middle Eastern Tech Founder Seeking Endorsement for Innovator Founder Visa
The Scenario: An entrepreneur from Dubai developed an AI logistics platform and sought endorsement under the UK Innovator Founder route. To prove past business success and commercial viability, the endorsement body demanded historical audited corporate tax returns and VAT filings from their UAE mainland and free zone enterprises.
The Evidentiary Challenge: Corporate tax in the UAE involves both Federal Tax Authority (FTA) corporate tax returns in Arabic and English, alongside audited financial statements prepared according to IFRS standards. The endorsement panel required complete statutory verification that past revenues were genuine operating turnover rather than inter-company shareholder loans.
The Solution: Lang247 translated and certified the complete 60-page financial filing, verifying balance sheet notes, auditor certifications, and tax registration numbers. The endorsement body approved the application, granting the founder the mandatory endorsement letter for UKVI.
Step-by-Step Workflow for Certified SA302 & Tax Return Translation in the UK
To ensure total compliance with Home Office legalisation and translation standards, applicants should follow this structured step-by-step workflow when preparing foreign tax returns for UK visa submissions:
- Step 1: Procure Original Digital Tax Certificates from Official Portals: Access your overseas national revenue service portal (such as the IRS, CRA, or national tax authority) and download the official, digitally signed PDF copies of your tax assessments, notices of assessment, and payment receipts. Ensure that all watermarks, electronic verification barcodes, and reference codes are crisp and legible.
- Step 2: Check for Multi-Currency and Exchange Rate Conformity: UKVI assesses all financial figures in British Pounds Sterling (£). When submitting foreign-currency tax records, include the official OANDA or HMRC monthly average exchange rate applicable to the closing date of the relevant tax year. Ensure your certified translation reflects the original currency denominations accurately without arbitrary conversion.
- Step 3: Engage an Accredited Professional Translation Provider: Commission an established UK certified translation organization such as Lang247. The translation team must possess specialized legal and financial expertise to accurately render complex fiscal terminology, statutory tax code citations, accounting deductions, and corporate governance classifications.
- Step 4: Formal Execution of Statement of Truth and Seal: The accredited translation agency reviews the final translation against the original tax computation, executes the formal Statement of Truth, affixes the translator's official registration credentials (ITI / CIOL / ATC), applies the corporate seal, and signs and dates the document.
- Step 5: Digital Collation and Portal Upload: Collate the certified English translation sequentially with the original foreign-language tax certificate into a single, high-resolution PDF file. Upload the consolidated document into the designated "Financial Evidence" category of your UKVCAS (Sopra Steria), TLScontact, or VFS Global biometric appointment portal.
Glossary of UK Tax Terminology vs International Fiscal Equivalents
To assist cross-border applicants and legal practitioners, this statutory glossary highlights the key terminology used across UK tax filings and their direct international equivalents:
| UK Tax Concept | HMRC Definition | US Equivalent | EU / International Equivalent |
|---|---|---|---|
| SA302 | Official HMRC calculation of taxable income and final tax liability. | IRS Tax Return Transcript / Form 1040 Tax Computation. | Avis d'imposition (France) / Steuerbescheid (Germany) / Notice of Assessment (Canada). |
| Tax Year Overview | HMRC online statement showing tax paid, outstanding balance, and interest. | IRS Account Transcript / Proof of Tax Payment. | Bordereau de situation fiscale / Certificato dei carichi pendenti tributari. |
| UTR (Unique Taxpayer Reference) | 10-digit unique number assigned to every individual and company registered for UK tax. | SSN (Social Security Number) or EIN (Employer Identification Number). | Numéro Fiscal / Steueridentifikationsnummer / Codice Fiscale / PAN. |
| PAYE (Pay As You Earn) | System where employers deduct income tax and National Insurance directly from salary. | Federal Income Tax Withholding / W-2 Wage Statement. | Prélèvement à la source / Lohnsteuerabzug / Ritenuta d'acconto. |
| P60 | End-of-year certificate issued by employer showing total pay and tax deducted. | Form W-2 (Wage and Tax Statement). | Certificato Unico / Déclaration annuelle des salaires / T4 Slip (Canada). |
| CT600 | Official company tax return form submitted annually by UK limited companies. | Form 1120 (U.S. Corporation Income Tax Return). | Déclaration régime réel / Körperschaftsteuererklärung / Modelo 200 (Spain). |
Common Evidentiary Pitfalls That Trigger UKVI Visa Refusals
Immigration caseworkers adhere to rigid compliance matrices when reviewing financial evidence. Minor evidentiary oversights in tax documentation routinely lead to administrative delays, formal requests for further evidence (RFE), or outright refusals. The most prevalent mistakes include:
- Uncertified Self-Translations: Submitting a translation performed by the applicant, sponsor, or a bilingual family member. The Home Office explicitly bars applicants or their immediate relatives from translating evidentiary documents, regardless of linguistic proficiency.
- Selective or Excerpted Translations: Submitting only the first page or summary box of a 15-page tax filing. UKVI rules mandate that every page, schedule, annexure, and official explanatory footnote must be fully translated.
- Missing Translator Credentials: Submitting a translation that includes a general disclaimer but fails to state the translator's professional accreditation number, organizational membership, business address, and telephone number.
- Mismatched Names and Tax Numbers: Discrepancies between the applicant's name on their passport and their name on foreign tax certificates (e.g., maiden names, differing transliterations, or missing middle names) without an accompanying certified change-of-name deed or official explanatory affidavit.
- Failure to Provide Evidence of Tax Settlement: Providing the tax return computation showing tax owed, but failing to provide the certified receipt or tax year overview demonstrating that the liability was settled in full prior to the visa application submission date.
Frequently Asked Questions Regarding HMRC SA302 & Tax Return Certified Translations
Can I use an online automated tool like Google Translate to translate my foreign tax return for UKVI?
No. The UK Home Office and UKVI categorically reject automated, machine-generated translations. Under official immigration rules, all translations must be executed and certified by a qualified, professional human translator who provides a signed Statement of Truth and full professional credentials.
Do I need to send the original paper documents, or are digital PDF certified translations accepted?
Since the nationwide implementation of digital document uploading across UKVCAS, TLScontact, and VFS Global portals, certified digital translations in high-resolution PDF format are fully recognized and accepted by Home Office caseworkers. The PDF must feature the translator's official digital signature, corporate seal, and verifiable credentials.
What information must appear on the certified translation certificate?
The certification statement must explicitly state that the translation is a true and accurate translation of the original document, provide the date of translation, include the translator or translation company's full name, contact information, and signature, and detail their formal credentials or membership in a professional translation body (such as ITI, CIOL, or ATC).
How should foreign currencies on tax returns be handled in the certified translation?
The certified translation must preserve the original currency figures exactly as they appear on the original tax certificate (e.g., USD, CAD, EUR, INR). The translator must not convert the figures into British Pounds directly within the text. If currency conversion is required for financial threshold calculations, the applicant should provide a separate calculation sheet citing official OANDA or HMRC exchange rates.
Does an SA302 translation require notarial execution or an FCDO Apostille for the Home Office?
No. For domestic UK visa and settlement applications submitted directly to the Home Office or UKVI, standard certified translation from an accredited translation body is fully sufficient. Notarisation or FCDO Apostille certification is only required if the document is being submitted to a foreign court or overseas consular mission.
What is the typical turnaround time for a certified tax computation translation?
Standard certified translation of an SA302 computation or tax assessment typically takes between 24 to 48 hours depending on document length and complexity. Expedited same-day services are also available for urgent visa application deadlines.
Why do UKVI caseworkers cross-reference tax returns with bank statements?
Under Appendix FM-SE and general financial guidelines, caseworkers must verify that declared taxable earnings correspond directly to net deposits entering the applicant's or sponsor's personal bank accounts. Any unexplained discrepancy between net income shown on an SA302 translation and banking deposits can prompt an evidentiary audit.
Can I combine foreign employment income with foreign self-employment income?
Under Appendix FM, applicants cannot easily combine self-employment income under Category F or G with salaried employment income unless both sources of earnings occurred during the exact same financial year and comply with the strict overlapping accounting period rules set forth in paragraph 13 of Appendix FM-SE.
Secure Professional Certified Translation Services with Lang247
Ensuring that your tax filings and financial records meet the rigorous standards of the UK Home Office is vital to securing your visa approval. At Lang247, our accredited legal and financial translators possess decades of specialized experience translating complex tax computations, SA302 equivalents, corporate balance sheets, and statutory revenue disclosures across more than 150 languages. Every certified translation issued by Lang247 comes backed by our unconditional 100% acceptance guarantee across all UKVI, Home Office, HMCTS, and HMRC legal workflows. Contact our dedicated London translation team today to request a rapid, fully compliant certified translation quote for your upcoming visa application.
